
Springer
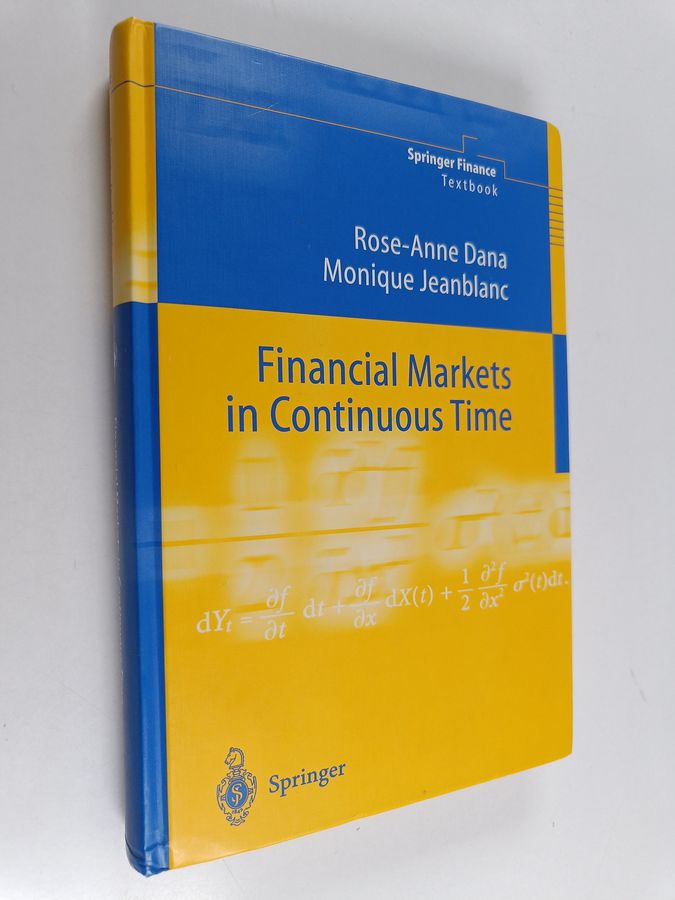
Financial Markets in Continuous Time
Alin havaittu hinta
Hinnat kaupoissa
1 tarjousHinnat ovat viimeksi havaittuja. Tarkista ajantasainen hinta, saatavuus ja toimituskulut kaupasta.
Hintahistoria
5 hintahavaintoaKaavio näyttää kunkin havaintopäivän alimman tallennetun tuotehinnan. Havaintojen välistä hintaa ei ole vahvistettu.
Hinta nyt 50,00 €. Alin havaittu 50,00 €, korkein 54,99 €. (-4 % keskiarvosta)
- Alin havaittu
- 50,00 €
- Korkein havaittu
- 54,99 €
- Viimeisin historian havainto
Näytä kaikki 5 hintahavaintoa
| Hinta havaittu (Suomen aika) | Hinta |
|---|---|
| 54,99 € | |
| 50,00 € | |
| 54,99 € | |
| 50,00 € | |
| 50,00 € |
Tuotetiedot
In modern financial practice, asset prices are modelled by means of stochastic processes, and continuous-time stochastic calculus thus plays a central role in financial modelling. This approach has its roots in the foundational work of the Nobel laureates Black, Scholes and Merton. Asset prices are further assumed to be rationalizable, that is, determined by equality of demand and supply on some market. This approach has its roots in the foundational work on General Equilibrium of the Nobel laureates Arrow and Debreu and in the work of McKenzie. This book has four parts. The first brings together a number of results from discrete-time models. The second develops stochastic continuous-time models for the valuation of financial assets (the Black-Scholes formula and its extensions), for optimal portfolio and consumption choice, and for obtaining the yield curve and pricing interest rate products. The third part recalls some concepts and results of general equilibrium theory, and applies this in financial markets. The last part is more advanced and tackles market incompleteness and the valuation of exotic options in a complete market.
- Brändi
- Springer
- EAN / GTIN
- 9783540434030