Springer
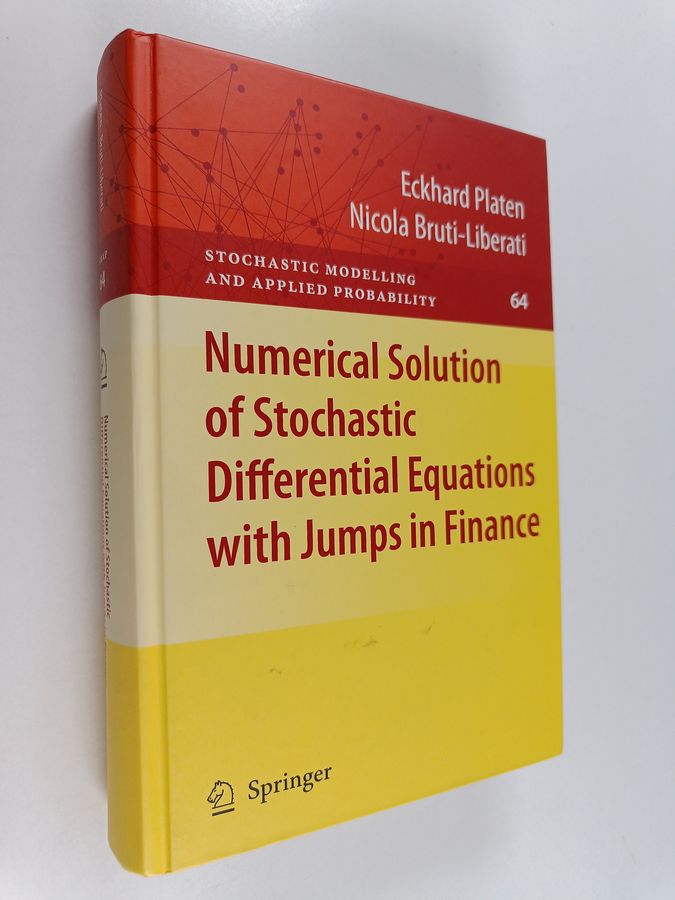
Numerical Solution of Stochastic Differential Equations with Jumps in Finance
Vertaa tämän tuotteen hintoja 2 verkkokaupassa. Halvin tuotehinta nyt 80,00 €.
Viimeisin hintahavainto: 20.10.2026 klo 10.41
In financial and actuarial modeling and other areas of application, stochastic differential equations with jumps have been employed to describe the dynamics of various state variables. The numerical solution of such equations is more complex than that of those only driven by Wiener processes, described in Kloeden & Platen: Numerical Solution of Stochastic Differential Equations (1992). The present monograph builds on the above-mentioned work and provides an introduction to stochastic differential equations with jumps, in both theory and application, emphasizing the numerical methods needed to solve such equations. It presents many new results on higher-order methods for scenario and Monte Carlo simulation, including implicit, predictor corrector, extrapolation, Markov chain and variance reduction methods, stressing the importance of their numerical stability. Furthermore, it includes chapters on exact simulation, estimation and filtering. Besides serving as a basic text on quantitativemethods, it offers ready access to a large number of potential research problems in an area that is widely applicable and rapidly expanding. Finance is chosen as the area of application because much of the recent research on stochastic numerical methods has been driven by challenges in quantitative finance. Moreover, the volume introduces readers to the modern benchmark approach that provides a general framework for modeling in finance and insurance beyond the standard risk-neutral approach. It requires undergraduate background in mathematical or quantitative methods, is accessible to a broad readership, including those who are only seeking numerical recipes, and includes exercises that help the reader develop a deeper understanding of the underlying mathematics.
Varastossa
Halvin tuotehinta
Katso kaikki 2 tarjousta80,00 €
Finlandia Kirja
Alin seurattu hinta: 80,00 €
Kannattaako ostaa nyt?
Hyvä hintaNykyinen hinta on hintahistorian perusteella tavallista edullisempi.
Nyt
80,00 €
Tyypillinen 90 pv
80,00 €
Alin 90 pv
80,00 €
Nykyinen hinta on käytännössä samalla tasolla kuin tyypillinen havaittu hinta.
Perustuu 38 ParhainHinnan havaitsemaan tuotehintaan. Tämä on hinta-analyysi, ei kaupan ilmoittama alennus.
Numerical Solution of Stochastic Differential Equations with Jumps in Finance hintakehitys
Hintahistoria · 38 seurantapäivääHavaittu tuotehinta on pysynyt vakaana seurantajakson aikana.
Hintahistoria näyttää päivän alimman havaitun tuotehinnan. Toimituskulut eivät sisälly hintoihin.
Alin havaittu tuotehinta
80,00 €
Keskimääräinen tuotehinta
80,00 €
Korkein havaittu tuotehinta
80,00 €
Vertaa hintoja
| Kauppa | Tuotehinta | Saatavuus | Päivitetty | ||
|---|---|---|---|---|---|
| 1 | Finlandia Kirja | 80,00 €Seurannan alin havaittu: 80,00 € | Ei tiedossa | 20.10.2026 klo 10.41 | Kauppaan |
| 2 | Springer Nature Link Shop | 142,99 €Seurannan alin havaittu: 142,99 € | Varastossa | 30.9.2026 klo 00.34 | Kauppaan |
Näytetään 2 / 2 tarjousta
30 päivän ja koko seurannan alimmat hinnat ovat ParhainHinta.fi:n omia havaintoja kyseisestä kaupasta. Ne eivät sellaisenaan ole kaupan hinnanalennusmarkkinoinnin lakisääteinen vertailuhinta.
Tekniset tiedot
- Books nl author
- Eckhard Platen; Nicola Bruti-Liberati
- Books nl publisher
- Springer Berlin Heidelberg
- Condition
- new
- EAN / GTIN
- 9783642120572
Samankaltaiset tuotteet
springer-verlag new york inc.
Mathematical Methods of Classical Mechanics
52,50 €
3 kauppaa · halvin: Adlibris