
Springer
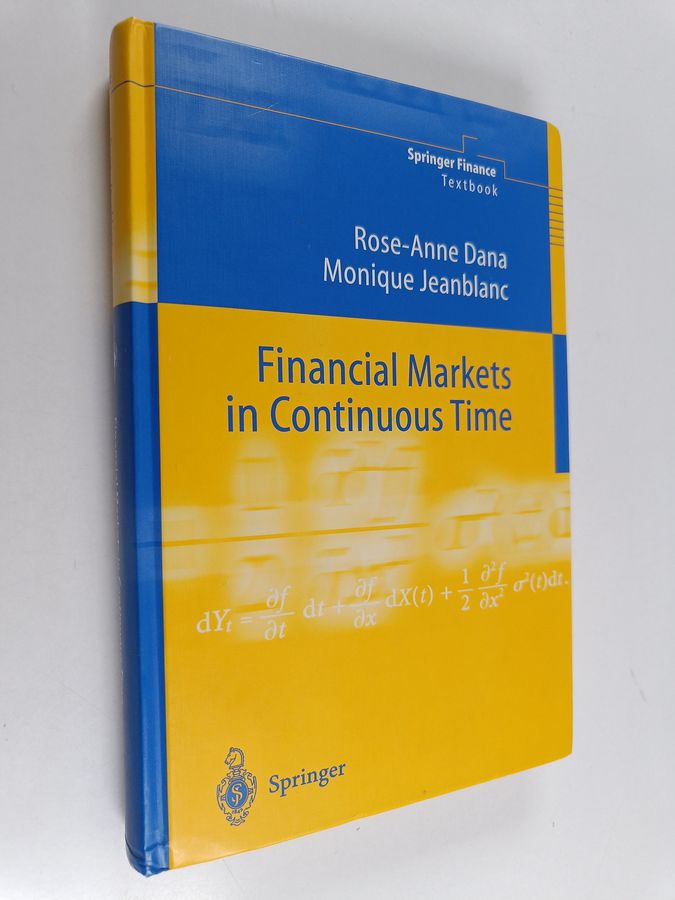
Financial Markets in Continuous Time
Lowest observed price
Prices at stores
1 offerPrices are the most recently observed prices. Check the current price, availability and delivery costs at the store.
Price history
5 price observationsThe chart shows the lowest recorded product price on each observation day. Prices between observations have not been verified.
Hinta nyt €50.00. Alin havaittu €50.00, korkein €54.99. (-4 % keskiarvosta)
- Lowest observed
- €50.00
- Highest observed
- €54.99
- Latest history observation
Show all 5 price observations
| Price observed (Finnish time) | Price |
|---|---|
| €54.99 | |
| €50.00 | |
| €54.99 | |
| €50.00 | |
| €50.00 |
Product details
In modern financial practice, asset prices are modelled by means of stochastic processes, and continuous-time stochastic calculus thus plays a central role in financial modelling. This approach has its roots in the foundational work of the Nobel laureates Black, Scholes and Merton. Asset prices are further assumed to be rationalizable, that is, determined by equality of demand and supply on some market. This approach has its roots in the foundational work on General Equilibrium of the Nobel laureates Arrow and Debreu and in the work of McKenzie. This book has four parts. The first brings together a number of results from discrete-time models. The second develops stochastic continuous-time models for the valuation of financial assets (the Black-Scholes formula and its extensions), for optimal portfolio and consumption choice, and for obtaining the yield curve and pricing interest rate products. The third part recalls some concepts and results of general equilibrium theory, and applies this in financial markets. The last part is more advanced and tackles market incompleteness and the valuation of exotic options in a complete market.
- Brand
- Springer
- EAN / GTIN
- 9783540434030