
Springer
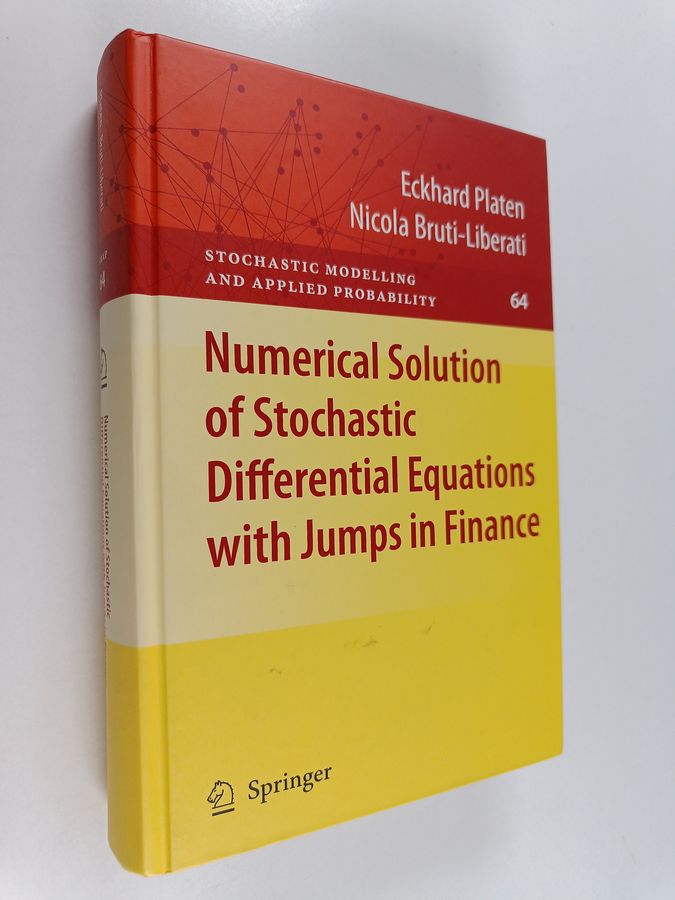
Numerical Solution of Stochastic Differential Equations with Jumps in Finance
Lowest observed price
Prices at stores
1 offerPrices are the most recently observed prices. Check the current price, availability and delivery costs at the store.
Price history
5 price observationsThe chart shows the lowest recorded product price on each observation day. Prices between observations have not been verified.
Hinta nyt €80.00. Alin havaittu €80.00, korkein €142.99. (-24 % keskiarvosta)
- Lowest observed
- €80.00
- Highest observed
- €142.99
- Latest history observation
Show all 5 price observations
| Price observed (Finnish time) | Price |
|---|---|
| €142.99 | |
| €80.00 | |
| €142.99 | |
| €80.00 | |
| €80.00 |
Product details
In financial and actuarial modeling and other areas of application, stochastic differential equations with jumps have been employed to describe the dynamics of various state variables. The numerical solution of such equations is more complex than that of those only driven by Wiener processes, described in Kloeden & Platen: Numerical Solution of Stochastic Differential Equations (1992). The present monograph builds on the above-mentioned work and provides an introduction to stochastic differential equations with jumps, in both theory and application, emphasizing the numerical methods needed to solve such equations. It presents many new results on higher-order methods for scenario and Monte Carlo simulation, including implicit, predictor corrector, extrapolation, Markov chain and variance reduction methods, stressing the importance of their numerical stability. Furthermore, it includes chapters on exact simulation, estimation and filtering. Besides serving as a basic text on quantitativemethods, it offers ready access to a large number of potential research problems in an area that is widely applicable and rapidly expanding. Finance is chosen as the area of application because much of the recent research on stochastic numerical methods has been driven by challenges in quantitative finance. Moreover, the volume introduces readers to the modern benchmark approach that provides a general framework for modeling in finance and insurance beyond the standard risk-neutral approach. It requires undergraduate background in mathematical or quantitative methods, is accessible to a broad readership, including those who are only seeking numerical recipes, and includes exercises that help the reader develop a deeper understanding of the underlying mathematics.
- Brand
- Springer
- EAN / GTIN
- 9783642120572